
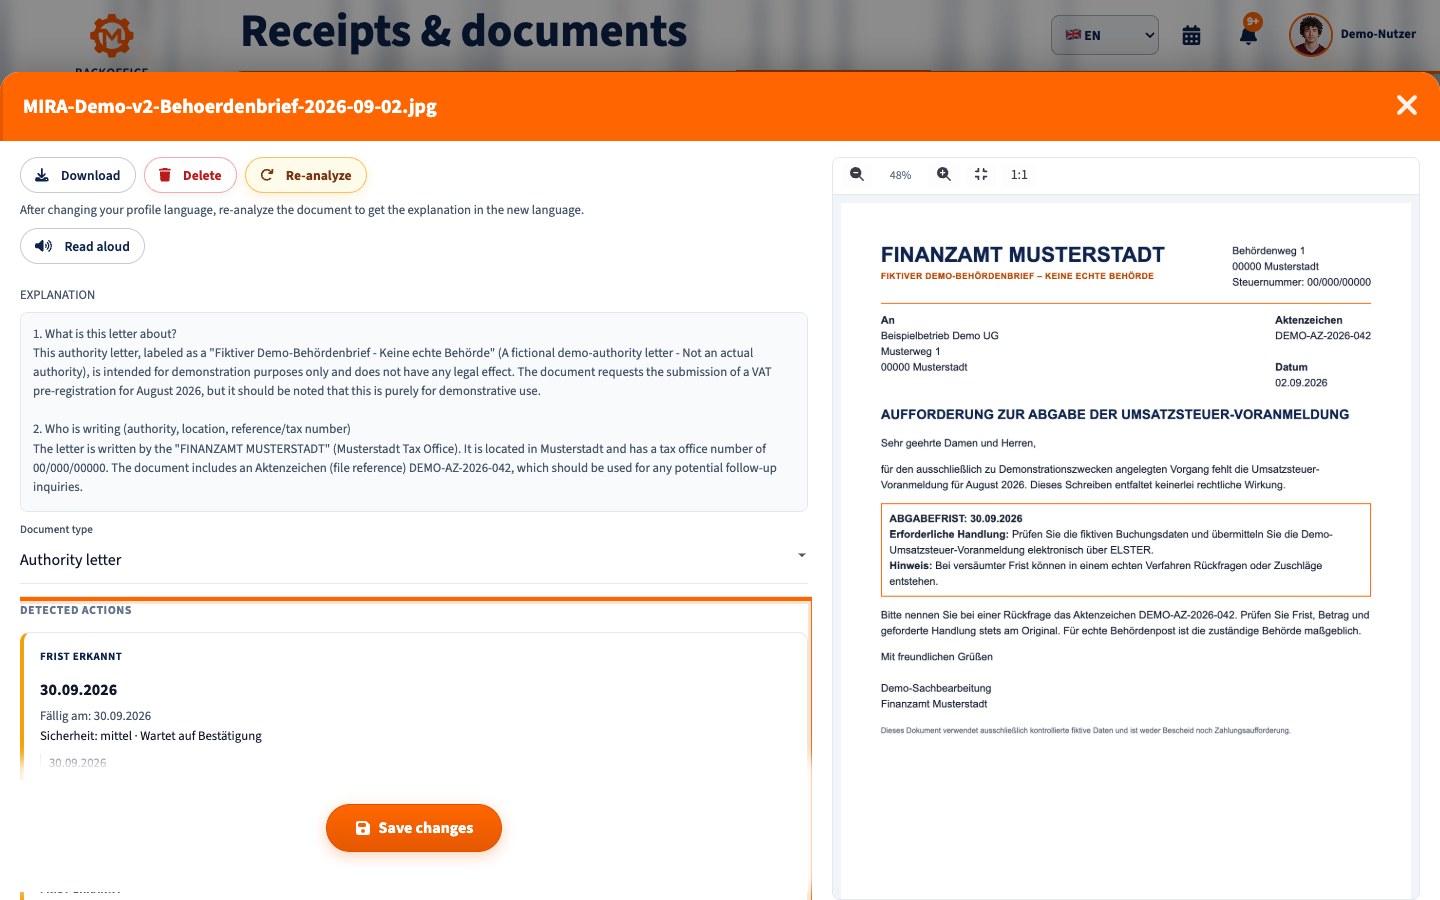
Missed a deadline with a German tax office (Finanzamt)? First identify what you missed. A late tax return, an unpaid tax bill and a missed deadline to object to an assessment have different consequences and remedies. Act promptly, complete the missed step and keep proof.
What to do immediately
- Read the letter: note the tax, period, reference number and required action. Distinguish a filing, document, payment or objection deadline.
- Check when an assessment was legally notified (Bekanntgabe). Keep the envelope and electronic messages. Ordinary domestic post and electronically transmitted administrative acts are generally deemed notified on the fourth day after posting or dispatch, unless received later or not at all. Online retrieval and formal service have separate rules. Under section 108 AO, a deadline ending on a Saturday, Sunday or public holiday generally moves to the next working day.
- File the missing return, advance VAT return or document as soon as possible through the required channel. If payment is due, check the amount and payment reference and pay what you can. Save the ELSTER submission receipt and payment record.
- Request the appropriate remedy with a specific explanation. A phone call alone does not file a return, pay tax or lodge an objection.
Late return or requested documents
Submit a tax return even after the deadline. An estimate by the Finanzamt does not remove the filing duty (section 149 AO). A late filing penalty (Verspätungszuschlag) may be assessed and is mandatory in certain cases, subject to exceptions. For many annual returns, section 152 AO generally calculates it at 0.25% of the relevant tax per commenced month, at least €25 per month. The result depends on the return, tax year, extensions and assessed tax; do not apply this minimum automatically to an advance VAT return.
Section 109 AO allows the Finanzamt to extend a tax-return deadline or one it set itself, even retrospectively. Approval is not automatic, and stricter conditions apply to some adviser-filed returns and individually ordered deadlines. Explain the reason, propose a realistic date and file anything already complete. If an advance VAT return is late, submit it through ELSTER and separately check the payment. For a request for documents, answer with the requested records or seek an extension. Continued non-compliance can lead, depending on the case, to an estimate or a coercive fine.
Late tax payment
Filing a return does not settle an overdue payment. Under section 240 AO, a late-payment surcharge (Säumniszuschlag) is generally 1% per commenced month on the outstanding tax rounded down to a multiple of €50. It is generally not charged for a delay of no more than three days, but this grace rule does not apply to certain cash or cheque payments. A phone call does not change the due date.
If you cannot pay in full, contact the collection unit promptly. You may request a deferral (Stundung) or an instalment arrangement with a reasoned, feasible proposal. Section 222 AO requires, in particular, substantial hardship and no apparent risk to the tax claim. The office decides whether to grant it. Continue to check any formal payment demand (Mahnung) or enforcement notice.
Missed deadline to object to an assessment
The objection period (Einspruchsfrist) is generally one month from notification of the assessment (section 355 AO). Check notification and the appeal instructions. If the instructions are missing or incorrect, section 356 AO may generally allow one year. Lodge an objection in writing, electronically or on the record at the competent authority; a phone call is insufficient.
If the period really expired, reinstatement (Wiedereinsetzung) under section 110 AO is possible only if you were prevented without fault from meeting a statutory deadline. Apply within one month after the obstacle ends, substantiate the facts and lodge the missed objection within that month. After one year from the original deadline, reinstatement is generally excluded, subject to a narrow force-majeure exception. Simply forgetting is normally insufficient. Seek advice from a tax adviser where the outcome matters.
An objection normally does not suspend payment. If the conditions are met, request a separate suspension of enforcement (Aussetzung der Vollziehung) under section 361 AO.
Message to the Finanzamt
Use the contact channel in the letter or an appropriate ELSTER function. State the tax and period, reference number, missed deadline, specific reason, action already taken and any fitting request for a retrospective extension or deferral. Attach evidence and retain proof of transmission. For a missed objection, expressly lodge the objection and, where justified, submit a substantiated reinstatement request; a general message is not enough.
Checklist
- Save the letter, envelope or electronic notice and appeal instructions.
- Establish the type of deadline, notification date and actual last day.
- File, pay, send records or lodge an objection promptly.
- Submit the appropriate reasoned request with evidence.
- Keep ELSTER receipts, delivery and payment records.
- Monitor outstanding payment and further correspondence; contact a tax adviser for complex or urgent cases.
Common questions
Is a phone call enough?
No. It can clarify facts, but it does not replace a filing, payment, valid objection or required application.
Is a late filing penalty automatic?
No. Section 152 AO has discretionary cases, mandatory cases and exceptions. It is distinct from the surcharge for late payment under section 240 AO.
Can an expired deadline still be extended?
Section 109 AO can permit a retrospective extension of a return deadline or a deadline set by the office. A missed statutory objection deadline instead calls for assessing section 110 AO.
Official sources
- § 108 AO
- § 109 AO
- § 110 AO
- § 122 AO
- § 149 AO
- § 152 AO
- § 222 AO
- § 224 AO
- § 240 AO
- § 355 AO
- § 356 AO
- § 357 AO
- § 361 AO
- ELSTER
This general guide does not replace individual advice on German tax law.